Friday, March 30, 2012

Survey of Surveys: Budgets and Process are Main Barriers to Marketing Technology Success

I recently gave a Web presentation comprised almost entirely of slides from different surveys. This was a bit of an experiment and, sad to say, it didn’t seem terribly successful. I did weave the slides into a nice little story line – marketers know they need better technology, poor data is the root of their problem, and we know how to solve this – but even that wasn’t enough. Pity.

Still, preparing the slides gave me a chance to scan the surveys in my archives, which was entertaining in its own little way. Many surveys ask similar questions, which gave me some choices during my preparation. But I didn’t look carefully at how they compare.

Today I’ll do that. I’ve chosen one of the most popular questions: what are the barriers to marketing technology adoption? I have versions of this from seven different surveys within the past year.

Of course, each survey uses different terms. To make the comparison, I collapsed the various answers into a few reasonably-distinct categories, committing a certain amount of shoe-horning along the way. I then recorded where each answer ranked in each survey, compiled the results, and did a crude ranking with a combination of mathematical wizardly and body english.  (Multiple answers for the same survey indicate I placed several questions into the same category.)

Results are below.  I've shaded the first ranked answers in orange and the second and third ranked answers in yellow.


My first observation was the sheer inconsistency of the answers. Budget issues emerged as a clear number one, but they reached that rank on just four of the seven surveys and ranked quite low on the other two that included them. The second-ranked item (marketing process) was never listed first; it ended where it did because it had the most twos and threes. No other item was ranked first more than once or in the top three more than twice.

Things made a bit more sense when I looked at the survey audiences. Winterberry and Forrester were specifically about online marketing, Gleanster and Marketing Sherpa were B2B surveys, and IBM and the two CMO Council studies were of general marketers. Since most B2B marketing is also online, it makes sense to look at the first four as one group and the other three as another.

Now we see some interesting consistencies:

• Budget isn’t much of an issue for the online and B2B marketers, but dominant for the mixed marketers.

• Marketing process and marketing staff skills are major concerns for online and B2B but rarely mentioned by the mixed marketers.

• Senior management support, and to a lesser extent IT support and technology capabilities, are significant barriers for mixed marketers but don’t slow down the online and B2B groups.

• Metrics, organizational silos, and the economy are cited occasionally by both groups but don’t seem to be major issues for either.

So there’s a fairly coherent picture after all.

• Online and B2B marketers are struggling to keep up with a rapidly changing marketplace, meaning their biggest problems are people and process. The importance of their work is obvious enough that budgets and senior management support are generally available. They have the technical savvy and independence to avoid issues with IT support and organizational silos.

• Mixed marketers, working in traditional channels, still struggle with budgets, metrics, and senior management. They have mature marketing organizations, so process and skills are in place, at least for traditional programs. They do struggle more with IT, technology, and organizational silos, because they lack their own technical skills and have limited clout in the organization.

• Everybody says they care about metrics but it's rarely a top priority.


Or at least that’s my take. I’ve displayed the actual surveys below – if you reach other conclusions or spot any other patterns, let me know.


Sunday, March 25, 2012

Kwanzoo Builds Content for Cross-Channel Marketing

I first bumped into Kwanzoo about a year ago at a conference trade show and was frankly puzzled at what they offered. The mechanics were clear: a tool to generate HTML-based forms, surveys, banner ads, and social sharing links that could be used on Web sites or embedded in emails. What puzzled me was the advantage of this over anyone else’s HTML content, including the content that could be generated using standard tools within most marketing automation systems.

Since this particular mystery ranked somewhere between the fate of Amelia Earhardt  and Nacza Lines  in my personal priorities, I didn’t investigate further. But the company reached out to me recently and provided a clearer explanation. Here’s the story.

What makes Kwanzoo special is it creates a sequence of Web pages that can be deployed as a single unit. A typical sequence would be a survey followed by different offers depending on the visitor’s answers. The entire sequence is built in Kwanzoo and deployed as a code snippet which displays the survey and calls the subsequence pages from Kwanzoo when appropriate. The second thing that makes Kwanzoo special is that its pages can be deployed on a client’s own Web site, on external sites and ad networks, embedded in emails, within Facebook, or on a mobile device. Users can also apply Kwanzoo tags to conversion pages to track results.

These capabilities make Kwanzoo substantially more versatile than a conventional marketing automation system, which would rely on campaign flows or manually-embedded links to manage the page sequence and could only deploy on emails or microsites generated by the marketing automation system itself. By contrast, users design the flows by filling out a simple form within Kwanzoo and then receive HTML snippets – simple calls to Kwanzoo-hosted URLS – that can be embedded anywhere. Kwanzoo also provides a powerful editor to build the Web pages and offers.

Data captured by Kwanzoo can be directly posted to Eloqua, Marketo, Constant Contact and Salesforce.com. The Eloqua integration is especially elegant, using an Eloqua Cloud Connector (i.e., a parameterized API call) that makes the Kwanzoo pages available within Eloqua’s own content builder and can read Eloqua cookies in real time to help guide the response selection. Integration is on the way with other marketing automation and CRM systems.

Users can also apply IP-address-based visitor identification to tailor responses to named accounts and different industries.

Kwanzoo says this versatility addresses some critical pain-points for marketers, including needs to create content and capture data across multiple channels and to create more personalized interactions. True enough.  But the system has its limits, most notably that sequences are limited to a couple of steps, a few data inputs, and a handful of actions, and that it doesn't maintain its own marketing database.

In other words, Kwanzoo is more a bridge between different marketing channels than an integrated marketing system. It’s easy to imagine Kwanzoo-captured data making its way back to multiple systems (marketing automation, CRM, Web site, mobile, etc.), which is not the ideal situation. There’s certainly a market today for this approach: Kwanzoo has landed about 25 clients since its launch in 2010 and seems to be growing nicely. Still, you have to wonder whether integrated platforms will eventually add similar capabilities tied directly to their own databases, making Kwanzoo’s external bridge less necessary.

Or, even more directly, will Adobe offer pretty much the same capability?  They already have the dominant tools for content-building (Dreamweaver, etc.) and Web visitor tracking (Omniture), which are the two key pieces of Kwanzoo's offering.  I long ago predicted that Adobe would combine these to create "smart content" that would adjust to customer behavior, although so far Adobe hasn't listened.  But they could.

But that’s Kwanzoo’s problem, not yours or mine, eh? At the moment, it’s worth a look. Pricing is based on number of impressions and starts as low as $499 per month to put Kwanzoo units on Web pages.  It quickly rises to $2,499 to embed units in emails, post data other than basic lead capture, support mobile formats, and use IP-address information for targeting.  


Friday, March 16, 2012

Salesforce.com Announces Site.com Web Site Management: Will Marketing Automation Features Follow?

Salesforce.com yesterday announced the launch of Site.com, an enterprise-class Web site management system. The news didn’t seem to get much attention, perhaps because Salesforce.com itself pretty much buried it. But Salesforce.com VP of Product Management Anshu Sharma did post a detailed explanation of the rationale on a Salesforce.com blog.

My original reaction was “I told you so”, since I’ve been talking about the convergence of CRM and Web site management for years. (Here’s a piece from 2009.)  Sharma’s reaches a similar conclusion although he puts it in a larger context of social media (people expect to interact with a company Web site like they interact on social media), cloud,  and mobile computing (marketers need content that can be presented on all types of devices). So far so good, especially since multi-channel content is another trend I’ve been toying with for some time.  (Not that I'm bragging or anything.)

Just to clarify my argument, the case for convergence between CRM and Web site management boils down to the fact those are the two main systems that companies use to interact with consumers. The move closer as Web sites capture more individual-level information and present more personalized treatments. And, as the two giants converge, the marketing automation industry stands between them like a mushroom, waiting to be crushed or gobbled up (if giants eat mushrooms).

Some of that gobbling has already begun.  Web site management vendor SDL purchased Alterian last November and sales enablement vendor CallidusCloud bought LeadFormix in January. Ironically, speculation about Salesforce.com itself buying a marketing automation system had pretty much died down since last August’s Dreamforce conference, when the firm made it pretty clear they didn’t have plans in that direction (notwithstanding their earlier HubSpot investment).

That’s why I was greatly intrigued by Sharma’s statement that the transformations created by social, cloud and mobile technologies “can only bear long-term fruit and deliver on the full promise of a 'digital marketing platform' when marketing and IT are a true partners.”

 That’s the first Salesforce.com reference I can find to a “digital marketing platform”.  It certainly implies something that includes marketing automation functionality. Maybe the reason Salesforce.com decided not to purchase marketing automation system because they figured same functions would evolve organically from a combination of CRM and Web site management. That’s probably correct, although it would take longer than adding those features directly.

In any event, the combination of CRM and Web site management gives Salesforce.com an integrated database containing all the information needed for effective marketing automation. Building marketing automation features to exploit that information then becomes a lot easier than building a complete marketing automation system.  This applies whether the system providing those features comes from Salesforce.com or an AppExchange partner, and it means the barrier to entry is lower than ever.  In short, the Site.com announcement is big news for the marketing automation industry, whether people recognize it or not.

Wednesday, March 07, 2012

BI Vendor QlikTech Reveals QlikView Pricing: I Modestly Help to Clarify

Business Intelligence software vendor QlikTech* officially published its price list last month, after years of keeping it a not-very-closely-held secret. I was personally pleased, since people occasionally ask me what QlikView costs.  But then I looked more closely at the list and realized I wasn’t quite certain what it meant. Happily, it didn’t take long to set up a briefing and clarify matters. Just in case anyone else is also confused, here’s what they told me:

- The lowest entry price for a fully functional version is $1,350. Although this is called a “Named User License”, it does NOT require connection to a server—the specific point I wasn’t sure of. What distinguishes this from the free Personal Edition is that the Named User License can read QlikView files created on other machines, while the Personal Edition cannot. Thus, a company could buy two Named User Licenses for $2,700 and those systems could share files back and forth.  Let me state clearly that as a confirmed QlikView fan, I think this is a terrifically low entry price.

- Companies with many infrequent users can purchase a “Concurrent License” that allows one user at a time for $15,000. This figure is so high that I thought it might be a typographic error, but QlikTech assures me it’s correct. In fact, they say it’s a bargain because they’ve found many clients can share more than 11 users on one license. These would be salespeople or other non-analysts who want to occasionally view a report. It seems to me that Murphy’s Law would ensure they all access the system during the same five minutes – presumably the evening before their monthly reports are all due – but I’ll take QlikTech’s word that this isn’t the case. After all, they're the analytical experts, eh?

- Companies who don’t want to spend $1,350 for casual users have some other options. These include a $350 “Document License” for one user for a single document, a $70,000 “Information Access Server” allowing unlimited users to access a single document (usually over a public Web site), and a $3,000 “Extranet Server Concurrent License” that allows one external user at a time to read documents on an $18,000 “Extranet Server”.

There are various other licenses for larger systems and special purposes. The descriptions are more or less self-explanatory, but of course you’d want to talk to QlikTech itself for detailed explanations.

One thing you definitely won’t find is a free or low-cost  “reader” licence that lets users view but not change a QlikView document. This is a disappointment to me personally, since we at Left Brain DGA use similar readers to send reports to our clients today. I can’t see those clients paying for Named User Licenses or Concurrent Licenses. But QlikTech is philosophically opposed to the idea of a limited-function reader, which it argues “goes against the current trend toward the democratization of software — in which line of business users can become as adept with an analytics tool as any business analyst or developer.” I can’t say I agree: QlikView takes considerable effort to learn, and many business users don’t have the time, need, or inclination to bother. They would be perfectly happy to consume existing reports without drilling any deeper, but are unlikely to pay $1,350 for the privilege.

I can’t judge how much business, other than mine, the lack of reader is costing QlikTech. Surely some people end up buying the full Named User License and using it as a reader, which makes up for some of the people who don’t buy at all. QlikView also has a strong argument that their total cost of ownership is lower than competitors, even at current pricing levels. The company grew 40% year-on-year as of its last financial report, so they’re clearly doing just fine with their existing approach.

_________________________________________________
* QlikTech is the company, QlikView is the product

Wednesday, February 29, 2012

SAS Unveils High Performance Analytics Technology

I spent the early part of this week at SAS’s annual analysts conference, where the company reviewed the past year and presented its vision for 2012. The story this year was simple: “big data”, and SAS’s “high performance analytics” approach to taming it.

Of course, “high performance analytics” is what SAS has always done and, like “big data” itself, the term is relative. What SAS specifically presented was a re-engineering of its core analytical procedures to run in “shared nothing” multi-processor environments.  Each data set is split into pieces that are loaded into separate units, processed independently and simultaneously, and then brought together for a result. SAS cited tremendous performance improvements, such as reducing the time to build a loan default model on a billion rows of records from 11 hours to 50 seconds. This obviously makes possible new, tactical applications.

The high performance architecture is becoming available in stages as each SAS procedure is rewritten to support it.  The change from a customer perspective is purposely minimal: existing SAS procedure calls are simply modified by adding a "HP" prefix.  This will make it easy for clients to take advantage of the new capabilities. 

The company revealed a just a few new products at the conference, most notably a Visual Analytics tool that uses in-memory processing to render billion-row data sets in seconds. But the real benefit of high performance will come less from new products than from using it with existing SAS procedures and tools. The SAS product that may benefit most of all is SAS Decision Management, which creates rule-based decision flows that can call on scoring models and other analytics to help guide tactical processes. The product itself isn’t new, but high-performance analytics will let it do new things.

SAS’s “big data” story also included Hadoop integration and expanded cloud deployments. By the end of March (if I understood the roadmap correctly), SAS will be able to read from and write to Hadoop data sets, embed Hadoop commands within SAS scripts, and send SAS metadata to Hadoop. Over the coming year, it will support cloud deployments through a variety of enhancements related to virtualization, open APIs, and eventually an app marketplace. The cloud-based initiatives also support SAS’s own on-demand business, which grew 57% last year to reach more than $100 million.

These are all positive developments for SAS, which must certainly support "big data" to remain relevant.  The new capabilities will also create some business changes as SAS competes more directly with companies like IBM and Oracle to embed analytics within operational processes. SAS itself noted the company is now more involved in architectural discussions of how its systems interact with the rest of the enterprise infrastructure. Other issues may include educating non-technical users and providing technology to protect privacy.  SAS leaders seem to think they can leave those issues to others, but I’m not so sure.

The conference produced little news directly related to marketing systems.  The company reports 38% growth in marketing applications – which it reports under the label of “customer intelligence” – so that is clearly a healthy business.  But the product road maps showed just incremental improvements of existing products, without any major new offerings. Again, high-performance analytics will make new things possible without other changes in the products themselves. The high performance version of marketing optimization is due by the end of the year.

If you want more evidence of how little attention was paid to marketing systems: SAS's biggest recent piece of marketing-related news, last week’s acquisition of online ad server aiMatch, got exactly one mention during the day-long presentation and was positioned as simply filling a small gap in the marketing product line. The company did announce, very casually, that aiMatch would be extended to include ad buying optimization as well as its current ad-selling optimization. That struck me as a pretty big deal, since ad buying is the heart of an already-huge industry that’s clearly the future of marketing. Then again, it’s also an intensely competitive, heavily-funded space that’s crawling with advanced technologies. Although SAS's high performance analytics could have a huge impact on ad serving, that won't happen unless SAS makes a major commitment of people and money.  We’ll see whether they make one.

Sunday, February 26, 2012

Balihoo Offers "Local Marketing Automation" for Channel Partners

One of first marketing automation systems I ever saw – this would be during the Reagan Presidency – was a custom-built dial-up network to distribute collateral to farm equipment dealers. This and similar seeds have since sprouted into a forest of products that help brand marketers work with dealers, distributors, franchisees, and agents. Some of these channel marketing systems focus on lead distribution, some on locally-customizable promotion materials, and some on campaign management. All must mediate the delicate relationship between relatively sophisticated central marketing departments and their firmly independent channel partners.

These products are part of the marketing automation industry, although their specialized nature places them on the periphery. General purpose marketing automation vendors also compete for this business with what are usually called “distributed marketing” options. I keep a distant eye on the space because it’s relevant but there are too many choices to track it closely. The best I can do is make an occasional visit to see what’s new.

I made my latest foray last week after a briefing request from Balihoo. I accepted partly because Balihoo labels itself as “local marketing automation”, which includes the two magic words that most pique my interest. More important, channel marketing issues have cropped up several times recently in my consulting and are likely to be even more prominent in my work at Left Brain DGA.  So it was worth taking a look.

I’m glad I did. Balihoo is an impressive product that combines localizable (is that a word?) content distribution with pre-packaged campaigns in email, direct mail, mobile, online ads, print, and broadcast media. It also helps local partners set up their own Web sites and social network accounts, register with local directories and search engines, and record telephone as well as online responses. The company says these latter features are unique, and a couple hours of my competitive research seemed to confirm this.

As Balihoo’s tagline suggests, it is designed to provide a marketing automation system for each channel partner. Users set up a “my info” page with contact information, store hours, directions, and other details.  These are then pulled into promotion templates as needed, meaning that much localization is fully automatic.  This saves effort, ensures consistency, and simplifies changes. The system also stores a customer list – owned by and only accessible to the channel partner – which can function as a simple CRM system.

The heart of Balihoo is wizard-driven processes to set up different kinds of marketing campaigns. These can include “negotiated” media such as television, newspaper and radio ads, which are purchased and trafficked by Balihoo on the buyers’ behalf, and "non-negotiated" media, such as printed mailers, email messages, and Web search ads, which local marketers can purchased directly.  In all cases, the campaigns are set up by central marketers as templates that determine which elements, if any, the local marketers can change. Templates can include predefined options, such as a list of standard offers, that give local marketers some choice without allowing them complete freedom. The system can also require central approval before a campaign is released.

In addition to one-off campaigns, local marketers can subscribe to on-going programs such as a recurring “new movers” mailing based on purchased lists. The system supports event-triggered and multi-step campaigns, although Balihoo has found that most local marketers balk at entering the response details needed to maintain them.

Balihoo can automatically apply co-op dollars to locally-selected campaigns, billing local partners only for the net amount due. This is a major benefit by itself, compared with the usual method of having channel partners lay out the funds and then apply for reimbursement. When central marketers feel a particular program is extremely important, they can even fund it fully themselves.
The system also provides detailed response reports, including recordings of telephone responses – which the company has found are much more important for local companies than national marketers. Even though customer data remains with the channel partner, Balihoo inserts tracking codes and captures aggregate response information so it can judge the effectiveness of different programs.

Balihoo is purchased by the central marketing department and delivered on a Software-as-a-Service platform.  Brand marketers can reskin their instance to give it a company identity.  Pricing is based on the number of local marketers who use the system. A typical big company pays $200,000 to $300,000 per year, not including media fees (passed through at cost) and supplemental services such as local registration. These could be paid by either the local partner or the national brand. Balihoo entered the “local marketing automation” business in 2008 and now has more than thirty enterprise clients serving more than 100,000 local businesses. If you’re keeping score at home, it has received $17 million in venture funding.

*                  *                    *

Ok folks – what you just read is a perfectly adequate blog post.  I could easily stop here. But remember those several hours of research? I’m not letting them go to waste. Here’s a table that compares features in Balihoo and several competitors.  One big caveat is this is based on what I could glean from company Web sites, which don’t necessarily cover everything.


Analyzing this table is easily worth a post of its own but I doubt I’ll have time to write it. So I'll make do with a few quick observations:


- it's worthwhile to distinguish between distribution and syndication. Distribution refers to making materials available for local marketers to download and customize for themselves.  Syndication refers to sending materials that are already customized with the local company name, address, and contact information but the local marketers cannot change. Syndication gives more central control and saves the local marketers work. It makes particular sense for automatically pushing materials to partner Web sites.

- some systems just do content distribution and/or syndication.  Remember that this is the original function of channel marketing automation.  There are many more products than I listed here with this capability, and it borders on general purpose digital asset management and content management – sectors with literally hundreds of products.

- most vendors also support email and direct campaigns.  This is a distinct step up in complexity, since it requires loading and/or purchasing prospect lists.  It shares borders with several types of general purpose systems, including email, CRM, and marketing automation.

- once you get past basic content distribution and email/direct mail production, features vary more substantially.  This is where buyers will need to pay close attention to their current and future needs. 

- several vendors offer media buying. These may be automated for direct-purchased media or services for media requiring negotiation and trafficking. Either is a big step beyond basic content distribution.

- social media support is hard to find. Only a few vendors offer it and they provide different combinations of setting up social network sites for the local business; providing content to share in social networks; and providing tools to post social messages. This could be an important feature for vendors to add: local businesses need help learning how to make social media work.

- managing co-op funds is surprisingly rare. You’d think this would be a common feature, since it's a logical extension of content distribution. But either the vendors just don’t talk about it on their Web sites (unlikely) or they’ve found that clients have other ways to handle it. I’m dimly aware that there are specialized co-op accounting systems – but that’s a corner of the forest I’ve never explored.

- services vary greatly. From a vendor viewpoint, the purpose of services is to remove roadblocks that prevent clients from using their systems. As a result, services vary depending on the features the vendor is trying to support. The list includes creating marketing materials, buying media, managing data, training users, executing entire programs, and building custom software.


Tuesday, February 21, 2012

Quantivo Offers High-Volume Customer Analytics at a Modest Price

These are exciting times in the world of analytical systems. The Web has created new demands to handle unprecedented data volumes and semi-structured data. Cloud-based deployment offers near-infinite hardware scalability and flexibility.  Acquisitions by enterprise software giants have opened opportunities for smaller, more nimble alternatives. The result has been an explosion of companies using new techniques for managing and analyzing huge data volumes. Many, including Vertica, Aster Data, Greenplum, and Netezza, have also been assimilated by enterprise vendors. Others, including Paraccel, Kognitio, SAND Technology, and 1010data, have grown steadily while remaining independent.

Quantivo is part of this latest technical flowering. Its core is a data structure that sits somewhere between columnar – now the most common approach for analytical processing – and hierarchical indexes. Specifically, Quantivo identifies unique pairs of values within incoming records and stores each pair only once. It then builds new pairs by identifying unique combinations of each pair with another element (which might itself be previously-identified pair). For example, the first analysis might find all transactions that involve a specific product on a single date. The second pass might find all transactions with that product/date pair that were made by a given customer. The process repeats, working up a hierarchy of combinations. The system also tracks the number of times each pair occurs and the specific records involved, so the full detail of the original data can always be reconstructed. The system doesn’t build pairs for all possible combinations of data elements, although users can define several hierarchies if they want the same element to be part of several pairs. Indexes also allow analysis across pairs that are not directly built into the data.

Quantivo doesn’t hide the details of its approach, but it doesn’t talk much about them, either. This likely reflects a (correct) judgment that users will care more about the system’s benefits than how it works. Those benefits include data compression (typically 10% of the original volume), fast response, high scalability, flexible schemas, handling unstructured data, and efficient processing of queries that cause problems in standard SQL. The choice of hierarchy also inherently organizes data around “concepts”, which can be different from the physical structures of the inputs. Queries are relatively simple because users see only a flat list of data elements; relationships are managed automatically, behind the scenes.

Yes there are trade-offs. The data must be processed during the load – a computation-intensive task that takes longer than creating a simple columnar database. The schema must be designed, which requires some technical expertise and can lead to slower response for queries outside the expected paths. Non-SQL queries require a Quantivo-built user interface, meaning users cannot stick with their familiar SQL-based business intelligence tools.

Some of these issues are mitigated by Quantivo’s other major differentiator: it was designed from the start as a true multi-tenant cloud-based solution.  This means it can easily spread its workload across multiple servers and replicate data as needed to support higher data volumes (billions of rows), reduce load times (typically one to two hours per day for daily updates), and improve response time. Support for multiple hierarchies and queries across hierarchies also minimize the price of making a bad decision during initial schema design, since even unplanned queries will execute reasonably efficiently. Designing a schema is relatively simple: in fact, Quantivo plans to add self-service data provisioning, including schema design, in the near future.

The Quantivo user interface is purposely designed to look like other business intelligence tools: users get a list of measures and dimensions, which they drag into place to create pivot tables. They can create filters, define calculated values, add summary levels, and drill down to details. There are simple graphics such as bar and pie charts, but no advanced visualization.

The unique power of the system lies within the filters, which can select data that’s outside the standard dimensions. For example, a filter could select all transactions for customers who purchased a specific product – the type of market basket analysis that’s hard with traditional SQL queries. The system also calculates “association metrics” which compare the data across two groups, such as products in the baskets including product A vs. products in baskets including product B.

Quantivo pricing is based on data volume and complexity. A typical client pays $40,000 to $50,000 per year for 100 million to one billion rows of data, making the system remarkably affordable for a product of its type.  Most clients are using the system for customer data analytics, and the vendor has created connectors for SAP, Salesforce.com, Marketo, Responsys, ExactTarget, Omniture, Google Analytics, IBM, Microsoft, and NCR systems. Quantivo launched as a cloud-based service in 2008 and has an undisclosed number of paying clients.

Thursday, February 16, 2012

Et Tu, David: Why Raab Associates Became Part of Left Brain DGA

You may have seen yesterday’s announcement that Raab Associates’ marketing technology practice* has become part of LeftBrain DGA, an agency specializing in demand generation strategy and execution.   

My role at Left Brain will be to build the “optimization” practice, which means working on marketing analytics as well as technology.  I’m looking forward to deeper involvement in client marketing programs than the project-oriented work at Raab Associates allowed.  Left Brain and its clients are eager for the optimization work because many of their programs have now passed their initial deployment and need this sort of analysis and tuning. 

Left Brain’s readiness for an optimization practice reflects changes within the larger demand generation industry.  As B2B marketing automation technology worked through its initial deployments, the industry needed best practices to ensure successful implementation.  This meant marketing process definition, marketing/sales alignment, and program strategy.  It’s still important to execute those properly, and always will be.  But we now understand what the issues are and how to solve them.  The next frontier is refining and expanding existing programs, especially at larger organizations (a Left Brain specialty), which have the data volume and resources to support advanced analytics.  That requires new best practices and success histories for optimization.  That’s exactly what I’ll be working on.  It will be fun. 

If you’re wondering about this blog and my other activities as an industry analyst: my current intent is to continue.  My work at Left Brain will still require keeping abreast of technology developments, both for our internal use and at our clients.  It’s likely that my topics will shift a bit as my day job revolves more around analytics and less around vendor selection.  But, as I just suggested, this probably mirrors a shift of focus for the industry itself.  So, if the stars are aligned as I think, my topics will be more relevant than ever.

Regarding my traditional consulting work on vendor selection and technology analysis: I'll probably do less of it as other Left Brain work takes most of my time.  But I’m still here and happy to hear from people who need help in those areas.  If we can’t help you at Left Brain, we’ll recommend someone who can.

Finally, there's our VEST report, which is still available at the Raab Guide Web site.  We just released a new edition of that, so it will be current for at least six months.  What happens after that I can't say: it might vanish, we might continue it under the Left Brain banner, or it might find a new home.  But for now it's still a great resource for companies looking for in-depth information on B2B marketing automation systems, so make use of it while you can.

Incidentally, my new title at Left Brain is Vice President of Optimization, which manages to be both vague and bureaucratic.  I'm thinking I might prefer Lord of Optimization, or maybe just Oracle.  Other suggestions are welcome, so long as they're G-rated enough to put on a business card. Maybe we should have a contest.
______________________________________________________________________
* The rest of Raab Associates, a children's book marketing agency run by my wife, will continue to exist.  See her Web site at www.raabassociates.com.

Thursday, February 09, 2012

NurtureHQ Offers "Dead Easy Marketing Automation". Is That Enough?

I don’t know whether to laugh or cry.

New-ish marketing automation vendor NurtureHQ showed me its product recently. It’s really nice. Clean interface, easy to use, all the standard marketing automation features. Particular strengths in:

• split testing (separately for email subject lines and versions)
• lead scoring (automatically reduces scores from older events)
• CRM integration (Highrise, Capsule CRM, Sugar CRM, Salesforce.com, and an open API)
• marketing analysis (users can track multiple outcomes per campaign)
• content management (nice email/form/page builder, user-defined variables can be shared across messages to make changes easy)
• selection, segmentation, and campaign flow based on list tags (highly intuitive)
• low price ($495 per month for up to 20,000 contacts and 10 users with unlimited emails and landing pages and no annual contract)

In other words, this is a worthy alternative to Act-On, SalesFUSION, Net-Results, MakesBridge, Genoo, and other small business systems. Definitely take a look if you’re in that market for that sort of product.

But there’s my problem: “that sort of product” is widely available already. NurtureHQ hopes to differentiate itself as “dead easy marketing automation”, which it arguably is. But is it so much easier than the other products I just listed? I think not.  Regardless of whether it’s the easiest of them all, the difference isn’t likely to be large enough to matter.

Naturally, NurtureHQ disagrees. Before building its system, the company spent six months talking to current marketing automation users.  Many said they never progressed beyond email because the next step was too hard. This led NurtureHQ to believe that an even easier system could find a broader market than current products.

Other vendors have asked the same questions and reached the same conclusions.  But I’m beginning to think those marketers were really saying something else. What they found “too hard” wasn’t the software, but the planning and content creation needed for serious marketing automation. Without a clear understanding of what they wanted to do, they couldn’t figure out how to get the system to do it. That’s not a software problem.  Even a system that could build programs just by reading marketers' minds wouldn’t work if those minds didn't know what they wanted in the first place.

This isn’t a new insight. Marketing automation gurus have long argued that companies need to define their processes in advance of deploying a new system. The case was made yet again this week in an excellent blog post by Joby Blume, describing his former company’s struggles with marketing automation. (Be sure to read the comments). Howard Sewell of Spear Marketing Group made a similar point on his own blog. I reached the same conclusion myself in a post using data from a Gleanster report on marketing automation.

None of this means that “ease of use” is a bad strategy for NurtureHQ and others. On a practical level, ease of use helps sell systems to people who otherwise wouldn’t buy them. But vendors can't succeed if their clients fail – especially they rely on revenue from subscription renewals. So it only makes sense to sell marketing automation to companies without adequate processes, content, and other resources if those companies understand they’ll need to add those resources later. To really ensure success, vendors must actively help their clients through training and, in some cases, services to do the work for them.   Vendors including LeadLife, Genoo, and MakesBridge already offer low-cost service packages for their clients.  Other vendors also have service arms and agency partners to help out on a project basis. Third-party training resources such as the Marketing Automation Institute (where I’m a board member) can also help to fill the gap and benefit from substantial vendor funding.

What does this mean for the software vendors themselves? If the real keys to success are marketers’ skills and processes, does it really matter what’s in the software? To put another way, is marketing automation software already a commodity?

I hate to say it, but, to some degree, yes. There are certainly differences among products, both in capabilities and ease of use. But most marketers can find several systems that will meet their needs. This means vendors are increasingly competing on other dimensions including their own marketing and sales skills, cost structures, supporting services, pricing, and financial resources. As I pointed out last week,  it’s no coincidence that four of the five largest vendors are venture-funded (six of seven, if you include Infusionsoft and HubSpot). Another factoid that makes the point even more clearly: three of the four fastest growing received major new funding in the past year.

Still, I’m not entirely ready to give up on technology as a major differentiator. What’s needed is more radical innovation than a better interface. If the real barriers to success are creating content and identifying appropriate programs, then technology must address those directly. There are some already tools to help generate content, such as systems for news curation  and video posting.  I can't think of any products that recommend the right marketing programs, but proper analytics can identify patterns that reveal opportunities, and it’s perfectly conceivable that a rule-based system could check for known issues and make recommendations. HubSpot’s marketing grader does a something like this although it only examines externally-available information.

Of course, marketers will still have to create content and design programs. But better technology could dramatically reduce the necessary effort and move marketers past the deer-in-the-headlights paralysis of not knowing where to start. Vendors who really want to expand the market beyond the resource-rich few should look in this direction.


Tuesday, February 07, 2012

Raab VEST Report: Testing, Data Quality and Content Management Still Lag in Marketing Automation Products


My last post looked at data from our just-released B2B Marketing Automation Vendor Selection Tool (VEST) to understand general industry trends and identify the greatest areas of improvement. Today we’ll look at the VEST data to see what’s still hard to find. As before, the charts show three columns: change in feature availability over the past year among core marketing automation vendors; current availability among core vendors; and current availability among enterprise vendors. See the previous post for details on the calculations.

Split Tests: Formal split testing of different content versions or customer treatments is the heart of marketing optimization, but many B2B marketers still don’t have the time or resources to do it. Given the lack of demand, it’s not too surprising that many vendors don’t offer strong testing features.  Still, I feel they have something approaching a moral obligation to provide these features and encourage their use.  Note that splits within lists, the one testing capability that is fairly common, is actually the hardest for marketers to use.  Testing features are much more available among enterprise systems, whose clients are more likely to conduct tests as a matter of course.


Value-Based Selection: This is arguably the next step after dynamic content (see my previous post), since it uses calculated values rather than user-crafted rules to select marketing contents or campaign actions. Like dynamic content, it reduces the complexity of marketing programs while allowing them to be more targeted. It's still much harder to find than dynamic content although it is becoming more available.  Again, enterprise vendors have a substantial lead over the core systems.


Integrate with Direct Mail Printer: This is admittedly a small tactical issue, but it's interesting in its own way.  There’s apparently a resurgence of interest of direct mail generally and post cards in particular as a way to avoid ever-more-cluttered email inboxes and social media channels. This is one of the few features that are more common among micro-business systems than the core group.


Project and Content Management: These features are most important for large marketing departments that need coordinate work of many people. Most core marketing automation systems can track the creation and last change date of an item. But serious administration requires much more detailed control over who makes changes, approvals, and project management. As marketing programs get more complicated at all sizes of companies, these features will become increasingly important.


Data Quality: These are features that give marketers more control over the data that goes into their systems. Like split testing, data quality is widely recognized as important but often ignored. Availability of these features actually went down last year because several new core vendors provided below-average support. Enterprise vendors, with their more sophisticated client base, support these features fully.


Data Management: These features each reflect a certain degree of data management sophistication, although there’s a reasonable case that a separate company table doesn’t matter much in practice. The opportunity table is critical for revenue analysis, and you see here that it’s widely available. Custom tables are needed to extend the marketing database beyond inputs from the CRM system. They used to be fairly rare but are now available in more than half of the core products.   But half full also means half empty, so buyers still need to check carefully to ensure a particular vendor supports their needs.


Reviewing this list of features, only value-based selection is really cutting edge.  The rest have long been standard for consumer marketing automation products and enterprise B2B.  They're missing from core B2B marketing automation systems because most of their clients are smaller, less sophisticated companies who haven't needed them.  This may never change for vendors focused on small marketing departments.  But vendors serving larger companies will add these features as their clients discover they need them.

For more information about the B2B Marketing Automation VEST report, please visit www.raabguide.com/vest.

Sunday, February 05, 2012

Raab VEST Report: Marketing Automation Vendors Added Webinars, Social Media, and Dynamic Content in 2011

Last week's post took a horse race approach to data from our newly available  B2B Marketing Automation Vendor Selection Tool (VEST): who’s ahead, who’s behind, and who is coming on strong. But that’s more important to industry insiders than the marketers who actually use these systems. Real marketers care about what the systems can do.

The VEST survey, covering nearly 200 items per vendor, answers that question in glorious detail. You need to examine the report itself to see answers for individual products. But aggregate data provides important context for understanding where the industry stands and where it’s headed.

Let’s start with the basics. I group vendors into three categories depending on their primary customers.

  • “micro” vendors sell largely to businesses under $5 million in revenue.  These include Infusionsoft, HubSpot, and OfficeAutoPilot.
  • “core” vendors sell to B2B companies with $5 to $500 million in revenue.  These include LeadFormix, Marketo, Genius,MakesBridge, Act-On Software, Right-On Interactive, SalesFUSION, Net-Results, LeadLife, Pardot, Silverpop, TreeHouse Interactive, Eloqua, Manticore Technology, and eTrigue.
  • “enterprise” vendors sell mostly to companies over $500 million revenue. These include Aprimo, Neolane, and Oracle.

As you might expect, products for larger companies have more features available.


(In this and following charts, “feature availability” is the ratio the actual vendor scores to the highest possible scores. The scores are on a scale of 0 to 2, where 0 means a feature is missing, 1 means it is partly available, and 2 means it is fully available. Having a “partly available” option introduces some dangerous wiggle room for aggressive self-scoring, but it doesn’t seem to have been used abused too badly: just 14% of the scores are 1, compared with 21% at 0, and 65% at 2.)


Remember, though: more features is not always better. A feature important to a large enterprise can make a system less suitable for a small company where the feature won’t be used but still adds cost and complexity. The VEST addresses this by providing different weighting schemes for the three types of customers. These weights reflect the most important features for each category and sometimes apply negative values to features that make a system less suitable for the target group. Scores calculated with those weights show that the core and enterprise vendors do about equally well at serving their target markets. The micro vendors have a little more room for improvement.


Speaking of improvement, we can also see how the industry has changed by comparing the new VEST with scores from one year ago.  This brings considerable good news: the micro and core vendors are indeed adding features, especially in lead generation, campaign management, and reporting. Enterprise systems are already so powerful that new features don’t matter much.

(The decline in “scoring and distribution” for the enterprise category is a bit of a fluke: one vendor was replaced by another with weaker scoring and distribution features. Because there are only three vendors in the group, this has a large impact on the total.).


The change in weighted scores shows roughly the same story – so, for the most part, vendors are adding features that matter.


But enough generalities. What really matters is specific features. Today I’ll look at the areas of greatest improvement. A later post will list key features that remain hard to find.

I’ll focus on the core vendors, since those are the systems that most B2B marketers will purchase. Each chart below has three columns:
  • “change”: the change in feature availability among core vendors, compared with the January 2011 VEST.
  • “core”: the feature availability for core vendors in the January 2012 VEST
  • “enterprise”: the feature availability for enterprise vendors in the January 2012 VEST.

Let’s start with three areas that gained a lot of industry attention last year: Webinars, social media, and revenue management.

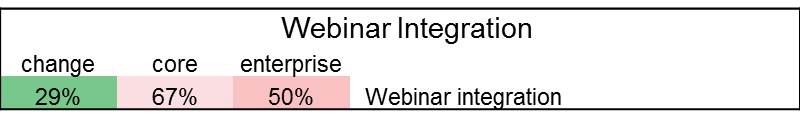
Webinar Integration: Webinars are an increasingly important marketing tool, but traditionally systems like Webex had their own registration forms and result tracking. Moving the information into marketing automation required time-consuming file extractions and imports. Last year, the Webinar vendors began to expose APIs to allow automated integration with the marketing automation systems, and the marketing automation vendors leapt on the opportunity. As a result, availability of Webinar integration grew rapidly. This is a rare area where the core vendors outscore the enterprise vendors, perhaps because the enterprise vendors are less narrowly focused on B2B needs and/or because they tend to move more slowly at enhancing their products.


Social Media: It’s no news that social media is a hot topic among marketers, so it’s no surprise that vendors are adding features to support it. But even after last year’s improvements, anything beyond basic sharing and tracking remains hard to find. This is another area where the enterprise vendors are lagging. For a more nuanced analysis, see my blog post Social Media Features in Marketing Automation Systems: Who Does What? from last December.


Revenue Management: We heard plenty last year from marketing automation vendors about revenue management. The good news is that they’ve backed up their words with features. In fact, it’s surprising how widely many key revenue management requirements are available – many industry leaders can walk this walk, even though a few do most of the talking. Note also that the enterprise vendors do most of this as a matter of course.


Okay, those were interesting but expected.  What else were vendors working on last year? Several things, it turns out.


Reporting: Enterprise vendors have long had better reporting than the core marketing automation systems.  They still do but the gap is closing. A separate analytical database is especially important for advanced analytics in general and for revenue management reports in particular. Again, it’s more widely available than you might think.


Dynamic Content: This refers to embedding content selection rules within an email, Web form, or landing page. It’s not just personalization, which simply plucks information from a database field, and it’s not segmentation, which uses rules to select different content objects within the campaign flow. Dynamic content lets one email or Web form serve different segments, so marketers don’t have to create and keep track of so many separate versions. As you’d expect, it was traditionally used in enterprise systems where complexity is a more pressing challenge. Core marketing automation vendors didn’t talk about it much last year, but quite a few seem to have added it.


Cross-Campaign Coordination: This encompasses several features to help coordinate customer treatments across campaigns. As with dynamic content, these become important when companies are running complicated marketing programs and need to keep things under control. It’s another area where core marketing automation systems are closing the gap with enterprise vendors, although some distance still remains.


Lead Scoring: remember that old Sesame Street song, “One of these things is not like the others”? You wouldn’t expect lead scoring on a list of most-improved marketing automation features, since it’s been a key marketing automation capability all along. But last year did see substantial rise in systems that provide multiple scores per lead, and a smaller rise in the ability to recalculate leads on a schedule (as opposed to when a trigger event occurs). Both are markers of advanced systems.  We may see lead scoring on next year’s most-improved list too: plenty of vendors still lack other advanced lead scoring features. (If you’re wondering about the negative changes, they happened because several new vendors entered the core group with limited scoring features.)


So that's the good news: changes in areas the vendors talked about plus some changes they didn't necessarily trumpet.  Look for my next post to learn where they still need to strengthen their products.

Of course, the only thing more exciting than reading my analysis is to make your own.  For more information about the VEST report or to order your own copy, visit the RaabGuide Web site.

Wednesday, February 01, 2012

New Marketing Automation Report: Venture Funding is Key to Success

I released the 2012 edition of our B2B Marketing Automation Vendor Selection Tool (VEST) report today, an event that deserves more hoopla that I’ve given it. The VEST provides by far the most detailed, objective information available on industry vendors. It includes nearly 200 data points on 21 products, thumbnail sketches of each vendor’s strengths and weaknesses, and three industry quadrants showing leaders in different market segments. It’s also interactive: you can change the weights assigned to different items and watch the vendors zoom around the quadrant as a result. For those of us who don’t get out much, that’s downright exciting.

Although the VEST is primarily intended to help people who are buying a marketing automation system, its database also provides a statistical portrait of the industry. After rooting around in the numbers like pig hunting truffles, here’s what I dug up:

Core marketing automation is growing fastest. We classify industry vendors into four groups:
- micro business vendors (Infusionsoft and OfficeAutoPilot)
- HubSpot (a category of its own because it’s not quite standard marketing automation and is big enough to treat separately)
- enterprise vendors (Neolane, Aprimo, Silverpop, and Oracle)
- core B2B marketing automation (everybody else: Eloqua, Marketo, Pardot, Genius, Act-On, et, al.)

The enterprise vendors don’t release meaningful installation counts – some refuse to provide any data and others don’t distinguish B2B from B2C clients. So we’ll exclude them from further analysis. The table below shows growth for the remaining groups:

As you see, core vendors grew almost twice as fast as the micro-business group and considerably faster than HubSpot. There was some speculation last year that the micro-business vendors were growing the fastest. Myth busted.

Revenue grew faster than installation counts. The previous table shows that combined growth across all categories is 46%. But that doesn’t mean much because the selling prices are so different. Adjusting for revenue per client, I estimate that industry revenue grew about 55% last year.  I could show you my calculations, but then I'd have to...well, you know.

New leaders can still emerge, but venture funding is required. A year ago, the three largest core vendors were Eloqua, Marketo, and Genius, and Act-On was an also-ran. Today, the Marketo has more clients than Eloqua (although not more revenue), Pardot has replaced Genius in the third position, and Act-On is coming up fast.


It's no mystery why the market remains fluid: venture capital lets new entrants shoulder their way to the top. Of the five top-ranked core vendors, all but Pardot has substantial venture funding. None of the remaining ten core vendors do – and their average growth is much slower. Self-funded firms can survive but it’s unlikely they will become leaders.

Specialization is increasing. We ask vendors for client counts in four segments: micro-business (under $5 million revenue); small business ($5 to $20 million revenue), mid-size business ($20-$500 million revenue) and big business ($500 million and higher). Most gave us answers, although Act-On was a prominent hold-out.

It’s no surprise that the micro vendors sell almost exclusively to micro clients. HubSpot’s base is much more diverse, although the micro and small sectors still account for 75% of its base. Of the core vendors, Marketo and Genius are the most small business oriented, with the two smallest categories accounting for over half of their customers. Pardot is tightly focused on small and mid-size clients, reflecting their disciplined sales approach. Eloqua has by far the most big-business clients of any core vendor, a proportion that has grown dramatically since the first VEST report one year ago.


For more information on the new VEST report, visit www.raabguide.com/vest.