Tuesday, April 15, 2014

Matching Marketing Technology to Business Strategy: A Starting Framework

As you may know, I’m working with Scott Brinker of Chief Martech blog fame and Third Door Media on the MarTech marketing technology conference set for August 19-20 in Boston.*

When Scott asked for content suggestions during the early stages of the conference planning, my reaction was that one thing everyone needs is a framework for relating marketing technology investments to larger business strategy. Scott was flatteringly enthusiastic and – I totally should have seen this coming – came back two weeks later with the suggestion that I present such a framework.

Bluff called.

Every consulting engagement I do starts with the relationship between business strategy and marketing technology.**   But I've always defined it on a case-by-case basis.  Until Scott asked, I never had a reason to create the framework for a generalized approach.

So, where to begin? The first thing to remember about strategies is that they’re about making choices: a strategy is a method for reaching a goal; knowing the method gives you a way to decide whether a particular choice is consistent with it.  More concretely, “make money” is a goal; “make money by building high quality products for which customers will pay a premium” is a strategy. Even a strategy as simple as that one tells you a great deal about where to invest, what kinds of systems to build, what kinds of marketing to perform, whom to hire, and much else. I do this analysis for my clients so we can be sure to find marketing systems that are consistent with their business approach and resources.

But here’s the thing: just about every discussion of marketing technology starts off with the (true) fact that today's customers demand a highly personalized experience informed by detailed knowledge of their history. The implication is that every business needs to adapt a strategy of customer intimacy. But if everyone has the same business strategy, then shouldn’t everyone use the same technology strategy as well?

[crickets]

I think the answer is no, for two reasons. First, everyone doesn’t have the same business strategy. Second, even the same business strategy could result in different technology approaches.

• Business strategies still differ. It’s true that customers today expect every company to track their interactions and respond intelligently across all touchpoints.†   But precisely because that expectation is universal, meeting it isn’t enough by itself to be a successful strategy. Remember, strategy is about choices and there’s no choice about whether to meet those expectations. It's HOW you meet those expectations that involves choices that are strategy-driven.

• Tech strategies can vary for the same business strategy.  Let’s say your business strategy is to be a low cost provider. You still have to deliver a reasonable degree of customer intimacy, just as you still have to deliver a reasonable degree of product quality. In this case, the goal of your tech strategy is always the same: “to deliver customer intimacy at low cost”. But the method could be “through extensive automation”, “through low labor cost via outsourcing”, or “through limiting services provided”. Each would imply a different technical approach.

Okay, the notion of a strategy-to-technology framework seems to make sense. [cheers]  So what would that framework actually look like?

It would start with strategic options. The classic big three are high quality, low cost, and high service (i.e., close customer relationships). Each implies different requirements for marketing, product design, production, customer support, and administration, which in turn drive technology, core competencies, and organization.††

Those requirements are the goals of the technology strategies. Methods to meet them are technology options, such as integrated suites, best of breed systems, and platforms-and-apps.  These are modified by other parameters such as in-house vs. outsource, scope of channels, sophistication level, resources, and scale. Note that some of these are choices while others are constraints.

The really critical challenge in setting your technology strategy is understanding the implications of each option so you can pick the technology strategy that best meets the business strategy requirements. Once the technology strategy is chosen, the final step is mapping the choices to the different layers of the marketing technology architecture: Data, Decisions, and Deployment (I just made that up but we all adore alliteration). The resulting framework would indeed be specific enough to give useful guidance. [more cheers]

I’m guessing this sounds like gibberish to at least some of you. Fair enough. Here’s an example of the framework for an online retailer trying to compete with Amazon by offering customers even lower prices. As you read this chart from left to right, each column provides guidance to the column that follows it.


The recommended strategy in this example is to buy an integrated suite and outsource its operation, accepting limited flexibility in return for lowest possible cost. You might not feel that suites actually give the lowest cost, but that's okay.  In fact, I recommended a suite specifically to make the point that the platform-and-app architecture seen as the future of marketing tech by many people (myself definitely included) isn’t always the right solution. Nor, alas, can a framework force you to make the best choice. What it can do is provide clarity about the options being chosen, so people can argue their case if they disagree, and then pull in the same direction once a decision is made.

So that’s what I’m thinking at the moment. It could well change by the time I reach Boston in August. Join us then and find out.

______________________________________________________________________________

* The conference will provide a much-needed vendor-agnostic forum for understanding marketing technologies and how organizations can use best them. If you’re reading this blog, you should attend. Click here for more info and early bird pricing.

** You do know I make my living by helping companies define their marketing technology requirements and select tools, right? Some people seem not to realize this.

† Well, maybe not every company.  Some still don’t identify individual customers. But even former bastions of anonymity like consumer packaged goods manufacturers now increasingly connect to customers through targeted advertising, social media, and promotions. So we can modify the claim to state that customers expect this tracking when they know the data could be available. It doesn’t change the rest of this analysis.

†† This is all basic “strategy map” stuff based on work by Robert S. Kaplan and David P. Norton. Wikipedia tells me that strategy maps are obsolete but I still find them useful.

Thursday, April 10, 2014

Marketo Conference: Small Changes, Big Picture

Marketo wrapped up its three day Marketing Nation conference yesterday, having once more displayed its own marketing prowess by attracting national media attention (see here and here) with an appearance by Hillary Clinton. Still, the real focus was on Marketo’s own announcements, which included several product changes and a new positioning. (I wasn’t at the conference but Marketo briefed me on their plans.)


The product changes were quite modest: new search engine optimization features for entry level users; a global marketing calendar; and relabeling of InsightEra, which Marketo purchased in December, as Marketo Real Time Personalization. The SEO and calendar features are still in beta and will be rolled out this spring and summer. Real Time Personalization already exists, obviously, and will remain a separate product that can work with any marketing automation system.

The company also announced a deal to use Acxiom data for personalization and, somewhat more interesting, to coordinate advertising messages purchased through Acxiom with email and Web site messages delivered by Marketo. This borders on integration of Web display with marketing automation, an extremely important trend. But it's Acxiom, not Marketo, doing the hard part of matching advertising audiences with identified individuals.

Marketo placed these changes in the context of unveiling itself as “customer engagement platform”. Ordinarily, I don’t pay much attention to these announcements: after all, Marketo has pivoted more than Ben Franklin dancing a gavotte. But Marketo had the hype-blasters turned to 11, so the news is impossible to ignore.

My main reaction was, what’s new? Marketo has described itself as a platform for at least a year now (see this press release, for example) and I’ve been talking about marketing systems as platforms for even longer. More important, the value of platforms has been widely recognized through the tech industry for decades: classic examples include Salesforce.com’s own AppExchange, Apple’s iPhone AppStore, Microsoft’s operating system software, and, going way back, the original IBM System 360. The appeal of the platform model is obvious: platform systems are quasi-monopolies (or actual monopolies), so their owners can charge high prices while the app developers compete brutally with each other and must keep prices low. Consumers are intuitively reluctant to accept the monopoly relationship, but usually trade away their freedom because no other choice available or in exchange for convenience and low total cost. App developers make a similar calculation, trading lower margins and less control for the larger marketplace and less development expense.

The trick to winning these benefits is becoming a platform in the first place. This requires a large customer base, easy access by app developers, enough power to be useful, and a barrier that keeps the monopoly intact. Salesforce.com, Oracle, IBM, Adobe, Microsoft, and other contenders to own “customer experience platforms” all did it the hard way, by first building up a big customer base for their conventional systems and then opening that universe as a platform to app developers.

Every major marketing automation vendor has tried to do the same.  But their customer bases are nowhere near as large, so what’s actually happened in most cases is that app developers have integrated their systems with multiple “platforms”.  One of the more subtle tricks in the platform playbook is to prevent this by making your system different enough from others that it isn't easy to support them as well.  This is usually done by means of a uniquely structured application program interface. But developers won’t put up with this unless a platform offers a big enough audience or other benefits to make it worthwhile. It’s doubtful that Marketo, or any other remaining independent marketing automation vendor, has the market power to do this.

Let me be clear. I’m not saying the platform approach is a bad one for Marketo.  I’m saying they lack the market strength to erect barriers to collect monopoly rents. They’ll have to keep their APIs simple enough that app developers can integrate with other marketing automation systems as well.  This means Marketo will be competing with other platforms for app developer relationships and can’t rely on Marketo-exclusive apps to attract new customers or prevent old ones from leaving. This is good news for app developers and marketers, if not for Marketo investors.

But it’s not enough to decide to be a platform. You have to decide whom the platform will serve and what functions it will include. In the case of customer management, the big question is whether the marketing system should be separate from sales and service systems. The obvious answer is they should be the same: after all, we want a unified customer experience across the entire life cycle, so all departments delivering those experiences should be on the same platform. Indeed, Marketo seems to imply as much with the term “customer experience platform”.

But in an excellent blog post describing the new positioning, Marketo VP Marketing and co-founder Jon Miller makes clear that Marketo believes marketers alone are in charge: “marketers are responsible for an all-consuming process that starts with attracting initial buyer attention and continues all the way to locking in customer loyalty and advocacy.” To remove any doubt, he later clarifies that the “customer engagement platform is the core system of record for marketing, just like CRM is the system for sales and Human Capital Management is the system for HR.”

I’d say this approach is debatable.  It will probably be harder for a marketing-owned system to integrate with customer-facing systems in other departments. Certainly other “marketing cloud” providers like Salesforce.com and Oracle would argue otherwise – that, at the least, there should be a shared customer database, and probably some shared processes to select customer treatments, even if those treatments are delivered by channel- or department-specific systems.

Marketo’s conclusion does position them as the best choice for marketing buyers, since they are the only marketing platform vendor with such a limited scope. To quote Miller again: “The marketing platform provider should be a partner to marketing, a company that truly understands what’s happening in marketing and that 'has marketing’s back'. Your marketing platform is not an add-on to sales technology, or a component of an IT solution. It’s the core foundation to all aspects of marketing success. That’s why at Marketo, we think that a marketing platform should come from a company 100% focused on marketing.” Fair enough.

The second big question is what’s included in the core platform and what’s provided by partners. In many ways, this is where the discussion moves from theory to reality, since there are specific choices to be made. Marketo’s published diagram lists three major functions at the platform layer – decisioning (a.k.a. “the brain”), database (“marketing system of record”) and analytics. They put an application layer on top of that, including marketing automation, interactions (real time personalization, search engine optimization, social marketing), and operations (marketing management). The third layer includes delivery in different channels (email, social, landing pages, sales, web/mobile personalization, search). APIs are available to connect each layer to third party applications.

My own definition of the platform layer is pretty much the same as Marketo’s. But Miller’s post lists six components of a marketing platform, corresponding to both the platform and application layers. And Marketo actually delivers functionality across all three layers. In other words, Marketo is not actually selling the platform by itself: it sells the platform in combination with applications and delivery systems, some of which are included and some of which are optional.

At first I thought this violated the platform concept, since the vendor’s own tools will likely have tighter integration with the rest of the system than the APIs make available to third parties. But, on reflection, there’s no requirement for a platform to be fully “application neutral”. Marketo seems to be proposing to sell a basic set of applications and delivery systems and let clients supplement them with third party applications as needed. APIs are an escape hatch for emergency use only, not Lego blocks that let users build a custom collection of products from scratch.

There’s a good case to be made for bundling the platform with applications and execution systems, boiling down to that it saves marketers from having to make a lot of choices before they get started. It also justifies a much higher price than the platform alone, especially if the monopoly position is unavailable. Of course, this ends up looking an awful lot like a traditional marketing software suite, which is exactly what Marketo was and remains under the hood. Marketers excited by the platform vision should look very closely at the reality before assuming that Marketo, or anyone else, can deliver the benefits they expect.

Wednesday, April 09, 2014

Vocus Purchased by Private Equity Firm GTCR: This Could Be Interesting

Vocus announced on Monday that they were being acquired by private equity firm GTCR  for $446.5 million in cash, a premium of 48% over their stock market price. It’s still a modest multiple of 2.4 x revenue, compared with the 6 to 7 x multiples paid for ExactTarget and Responsys by Salesforce.com and Oracle and the 14 x that Marketo commands in the stock market. I can think of several reasons for the discrepancy: GTCR isn’t a big software company looking to fill out an existing marketing suite; Vocus sells mostly to small business, not enterprises; Vocus hasn't created enough buzz.  But the main reason is probably that under 15% of Vocus' 2013 revenue came from its marketing automation products.  .

Vocus has been working hard to change its profile. When I wrote about them last July,
they had already created a Marketing Suite separate from their PR Suite. At that time, the marketing product was missing key marketing automation features including lead scoring, multi-step workflows, and integration with Salesforce.com. Those were all added last month.  Based on a preview the company provided me in February, the implementations are more than adequate for the small marketing departments that are Vocus’ core customers.  To give a flavor for the implementation: 
  • lead scoring holds separate scores for attributes and engagement activities; can assign activity points based on recency and frequency of email, Web visits, landing pages, and news release activity; and automatically recalculates scores over time.  But it only allows one score per customer.
  • workflows are built on a graphical flow chart; support yes/no branching on attributes and activities; can execute next steps immediately, after a specified period, or after an action is completed; and support actions including send emails, add the customer to another workflow, update a list, update a contact record, and remove the customer from the current workflow.  But it doesn't support a/b splits within the flows.
  • Salesforce.com synch is bi-directional and works with lead and contact records.  But it doesn't (yet) synchronize opportunities or custom objects.

Email, landing pages, behavior tracking, and reporting were already available in Vocus Marketing Suite, so the new features mean that Vocus now ticks all the major marketing automation boxes. It also still provides the advanced social media monitoring and influencer identification, press release posting, and local directory submission services that most competitors do not.  Plans include an expanded partner marketplace to make third party integration easier, expanded social marketing including social sign-on and social media campaigns, and anonymous visitor tracking without relying on cookies.  The vendor will also increase the sophistication of its core marketing automation functions, adding features such progressive forms, dynamic content, a/b testing for landing pages, and synchronization with additional Salesforce.com objects.

Beyond all that, my February notes include some vague but intriguing mention of automated analytics to help marketers do more effective lead scoring, segmentation, and workflow design. That kind of automation could be the key to expanding the number of marketing departments who can take full advantage of marketing automation opportunities.

To sum things up, GTCR has bought itself a very competitive marketing automation product for small to mid-size companies.  It will still mostly sell the business marketers but the social media, directory listings, and press release functions give Vocus more opportunity to serve consumer marketers than usual. The company now reports more than 8,000 marketing automation users,. expected to yield $40 million in bookings in 2014.  This easily makes it one of the largest stand-alone vendors in the industry. If GTCR allows Vocus to spend more freely on marketing and to continue improving its product, there is a good chance that Vocus can elbow its way to a top position in the hyper-crowded SMB marketing automation universe.


Friday, April 04, 2014

Bottlenose Offers Real-Time Trend Intelligence For Social Media and Beyond

I had an interesting briefing a few weeks ago from Bottlenose, which sells what it calls a real-time “trend intelligence” system. The general idea is almost boringly straightforward: monitor events as they occur and pick out new and interesting information. But the technology to make this happen is mind-bogglingly complex, since it includes real-time ingestion of diverse data types, several levels of natural language processing, and sophisticated trend detection.


To give some idea of the scale involved, the company said that simply monitoring “BeyoncĂ©” across social and broadcast media creates 220 billion (with a “b”) data points relating to 2 billion times series tracking more than 100 metrics on 2.5 million entities. The company currently stores trillions (with a "t") of observations for its current dozen or so clients, all big enterprises and agencies including Pepsico, General Motors, Microsoft, Digitas and Razorfish.

Bottlenose keeps up with the world pretty much the same way that you and I do: it scans news, social media, and other sources for information, extracts what’s relevant to our needs, and identifies new information or trends that might require some action. But while we humans can only process a tiny amount of information at each stage, Bottlenose works on another level entirely.

• Data sources. The system ingests huge swaths of social media, virtually every TV and radio broadcast in the U.S., U.K., and Canada (via automated speech-to-text conversion), Nielsen ratings and audience demographics, and stock market data. It can also accept other market and industry data, as well as a company’s own Web analytics, customer purchases and service interactions. This is all processed in real time, using technologies that handle thousands of messages per second per processor. The system can accept any data format from structured transactions to unstructured text.

• Interpretation. Specialized natural language processing extracts entities such as people and topics, identifies concepts and links, and assesses sentiment. This happens without predefined taxonomies or linguistics, although the system does work with nearly 100 rule-based, expansible classes of messages. It appends metadata to entities by matching them with other data sets, such as audience demographics for a TV broadcast. The system maintains profiles on 350 million individuals world-wide, including demographics, cumulative sentiment, language, geography, and social media influence.


• Trend identification. Bottlenose builds a time line tracking more than 150 metrics per entity, such as cumulative sentiment, audience size, influence scores, and demographics. Software agents constantly scan this data for trends, which could include connections, correlations, overlaps, clusters, or other relationships. When the system finds emerging trends that appear to be more than statistical noise, it highlights them in reports.

• Actions. Automated alerts for new trends are high on the Bottlenose agenda, but hadn’t been released when we spoke in March. What users get is a variety of interfaces that let them select a given topic, see relationships and what’s trending, and dig into as much detail as they want – all using real-time data. Key capabilities include seeing connections among topics, seeing the volume of messages and trends in sentiment, analyzing audiences demographics, and comparing statistics for two entities such as competing brands or media channels. Practical applications include identifying the most important influencers on a given topic, finding the most effective hash tags for social media, assessing advertising impact, and buying more effective media.

The underlying technology for all this involves a variety of tools, some proprietary.  The company calls its core processing stack "StreamSense" and says it uses several open source technologies including the Cassandra distributed database and Elasticsearch  real time search and analytics engine.  Although StreamSense is a platform that could be used for many purposes, the company so far has only offered it in conjunction with the Bottlenose trend intelligence application.

Of course, this platform potential is one reason I find Bottlenose so intriguing.  (The other is, it's just plain cool to work with so many kinds of data in such volume so quickly.)  Bottlenose is certainly not offering a Customer Data Platform, since its system is an application, not a central database available to external applications.  I'm not even sure that StreamSense meets the operational requirements for a CDP database, which have less to do with real-time analytics than easy access and flexibility.  But I do know that CDPs deal with higher data volumes and more varied structures than conventional databases can support, so I'm keeping an eye out for alternative technologies that might be better solutions.  Bottlenose might just have one.

Bottlenose was founded in 2010 and launched its original social media dashboard in 2011. It has expanded beyond the social listening category with its enterprise product, which adds TV and radio to social activity. Pricing starts at $200,000 to $500,000 per year, although some deals are larger.


Wednesday, March 26, 2014

IBM May Buy Silverpop: B2B Marketing Automation and B2C Email Would Be Great Fit

The InterWebs were buzzing this morning with an Atlanta Business Chronicle article reporting that IBM is negotiating to buy Silverpop. My only reaction was, What the heck took so long? The other enterprise-level B2C email vendors (ExactTarget, Responsys) have already been bought at wondrously high prices, and every B2B marketing automation vendor I talk to tells me that potential investors are approaching them constantly. So it was a totally safe bet that Silverpop was fielding many offers as well. With $50 million in funding, most of it provided years ago, it was an equally safe bet that Silverpop had some investors eager to cash out.

IBM as an acquirer also makes perfect sense. Although they bought B2C marketing automation leader Unica several years ago, they lack enterprise-scale B2C email engine and B2B marketing automation. This makes Silverpop a perfect fit.

The only surprise in this deal is the price, rumored to be about $270 million or 3x revenue. ExactTarget and Responsys both sold for 6-7x revenue and I would have expected Silverpop to yield something similar. The company has always been very tight with financial information, although client and employee counts they’ve provided for our VEST report suggest recent growth rates of 20% to 30% per year, which considerably lags the industry as a whole. We don’t know anything about profitability, but I’d guess they run close to break even, since they haven’t announced any new investment recently and the slow growth rate would reduce the need for capital. In general, the market seems to reward growth over profitability, so these results may depress their price somewhat.

The company’s mix of B2B and B2C clients may also confuse potential buyers and drive down the price a bit. Plus, there just aren’t that many enterprise software companies who still need what Silverpop is offering: Oracle and Salesforce.com have already made their purchases, Adobe is part of the way there with Neolane, and SAS and Teradata have their own tools and are probably less interested in B2B because most buyers are small or mid-size firms. SAP might be a potential buyer but hasn’t really shown an interest and just announced a deal to resell Adobe’s marketing suite. You could make an interesting case for Marketo as a buyer – to gain market share and some good technology, while leveraging a stock valued at more than 10x revenue – but that doesn’t seem to be part of their strategy.

So we’ll see. I wouldn’t be surprised if someone else offered Silverpop a higher price, but it’s not obvious who that would be. And if the IBM deal goes through, Silverpop will fit nicely into its new home.

Wednesday, March 19, 2014

IgnitionOne Buys Knotice, Prompting Many Deep Thoughts

Digital marketing technology vendor IgnitionOne today announced its acquisition of email and audience management vendor Knotice. Both vendors are listed in Raab Associates’ Guide to Customer Data Platforms in the “audience management” category. But the extract below from the CDP Guide also shows how they complement each other: Knotice does “fuzzy” matching of names and addresses and sends email, while IgnitionOne buys online media and selects best customer treatments. In other words, Knotice gives IgnitionOne a much stronger ability to incorporate non-Web channels and known individuals in its marketing and databases.

The only gaps shared by both systems are B2B clients and Web scanning for customer data, which is also mostly a B2B application. This further highlights the shift in industry acquisitions to B2C marketing technologies in general (ExactTarget/Salesforce, Responsys/Oracle, Neoalane/Adobe) and in audience data management platforms (BlueKai/Oracle, Aggregate Knowledge/Neustar) in particular.


These deals also reflect some other trends beyond acquisitions. One is the expansion of email vendors into broader multi-channel marketing. ExactTarget, Responsys, and Neolane all did this before they were acquired. StrongView (formerly StrongMail) and SmartFocus (formerly eMailVision) are making similar moves. SiteCore and SDL are moving in similar directions from a base in Web content management.

The second trend is a move by data-owning companies towards execution systems. Neustar, whose core business is linking people to phone numbers, is one example: it recently introduced “PlatformOne”, which it describes as a “centralized marketing solution” that gives marketers “a complete, real-time portrait of their customers and prospects based on accurate data, enabling a personalized dialogue across all marketing channels.”

V12 Group, another major data compiler, offers “Launchpad”, which “allows organizations of all sizes to build new audiences and manage existing customers using multiple channels and tools on a single platform.” Infogroup (which for some reason refuses to speak with me directly) in January announced “Yes Lifecycle Marketing” combining “email and digital marketing services, data, database technology, and agency services”. Venerable Acxiom has repositioned itself around the “Audience Operating System”, an “open platform” where “marketers, agencies and publishers can plan, buy and optimize audiences across channels, devices and applications, with precision and scale.”

Of the two trends, I think the second is more important. It’s not because execution systems are hard to find. Quite the opposite: they are essentially commodities, which is what makes it possible for so many data vendors to offer them. The significance is that consolidated customer databases are still very difficult to build, which is why there’s a Guide to Customer Data Platforms in the first place. A consolidated customer database is inherently part of the data vendors’ offering of execution systems, since the execution systems need to access a company’s own data to be useful.  This means that data vendors entering the execution market will compete to offer consolidated customer databases to marketers, hopefully at a much lower cost than the custom-built databases those vendors have traditionally provided. That these databases will combine digital advertising audiences with personally-identifiable names and addresses is pretty much a given, subject of course to privacy constraints. Many marketers will find hiring one of these vendors is an appealing alternative to building their consolidated customer database in-house.

Of course, today's real giants in compiling customer data are the companies like Google, Facebook, and Amazon.  They already sell advertising and do some customer data ingestion, and their resources dwarf the data vendors listed above. Don’t be surprised if any of them start building customer databases and offering execution systems. The only barrier is they may not think it’s a big enough business to be worth the trouble.


Monday, March 17, 2014

Marketing Automation Dissatisfaction: Are Users Buying the Wrong Systems?

I took a preliminary peek at the results of the marketing automation deployment survey that VentureBeat and I have been fielding for the past few weeks. There are some hints of really interesting insights, but we don’t have enough responses yet to publish. Like the sheriff in Blazing Saddles who held himself hostage, I'm writing this to encourage more people to complete the survey so we can release it.

First, some context. One of the rarely-spoken truths about B2B marketing automation is that a sizable minority of users – roughly one-third in most surveys – are not happy with their results. I wrote about last year in a pair of posts (here and here).  One purpose of the new survey was to probe for the reasons. We tested a number of possibilities: buyers are picking the wrong systems; they lack the skills to operate their systems; systems are too hard to use; marketing automation programs don’t deliver enough value to be worth the effort.

The results are open to interpretation but one figure jumped out at me: 25.9% of the respondents cited “missing needed features” as a top-three challenge in successfully using their systems. This wasn’t the most common answer but it still means that one-quarter of the users bought a system that didn’t meet their needs – that is, they bought the wrong system.


Answers about time spent on the search, number of systems considered, evaluation critieria, training, and staffing seem to consistent with this view. We’d gain some clarity if we could split the responders into groups: for example, were people who looked at more systems or searched for longer periods more happy with their selection?

This is where you come in, Dear Reader. We need more responses before we can publish the full results or do deeper analysis. If you’ve recently purchased a marketing automation system, please take the survey yourself and encourage others to do the same. Everyone who takes the survey will get a free copy of the report.

Thursday, March 13, 2014

Teradata Integrates Its Marketing Automation Acquisitions for Enterprise Marketers

Last year’s biggest marketing automation acquisitions were products for consumer marketing: ExactTarget by Salesforce.com, Neolane by Adobe, and Responsys by Oracle. But it would be wrong to see these as expanding the industry to a new set of users. Consumer marketers have had their own, highly sophisticated marketing automation systems for years. Products like Unica (now IBM), Teradata Customer Interaction Manager, and SAS Marketing Automation were introduced before the earliest B2B marketing automation systems and B2C email products. They’ve continued to grow their client bases, which are concentrated among large enterprises. As new entrants explore the world of B2C marketing automation, it’s important to recognize that the territory is already occupied.

I recently caught up with the folks at Teradata, which had its own marketing automation system for a decade before it acquired Aprimo marketing automation in 2011 and added Munich-based email vendor eCircle in 2012. The three products overlapped significantly, especially in campaign management, and it took Teradata a while to sort things out. But as of earlier this year, everything is now marketed as part of a Teradata Integrated Marketing Cloud including Marketing Operations (largely Aprimo’s marketing resource management technology), Campaign Management (the Teradata campaign engine with a sprinkling of Aprimo features and new user interface), and Digital Messaging (based on eCircle). The company also offers a suite of analytic applications for database management and predictive modeling.


The new user interface is the most noticeable change in Campaign Management’s latest release, version 7. But, bright colors and curly lines aside, what distinguishes it from other marketing automation systems is that nodes in a campaign flow can feed in customers from different database segments or Web interactions.  Most other systems do this audience definition outside the campaign flow.  The Teradata flows do continue with nodes that move through the program after they enter.  Users can assign separate paths to different treatment outcomes, such as an email bounce, open, or click, and can merge several paths into a subsequent node. Treatment nodes can be linked to data output templates and content templates, which can include dynamic blocks that are populated in real time when the message is rendered. Rules can limit the combined number of messages sent to each customer across all campaigns, with separate limits for messages of different types in different channels. These are advanced features for consumer marketing automation and almost unheard of in B2B systems.

Beyond the campaign interface, Teradata builds on its traditional strengths in data management and analytics.  It provides unified access to digital and offline data, automated predictive modeling, cookie-free Web behavior tracking through an alliance with Celebrus, user-defined response measures, posting of Twitter comments to customer profiles, and “extended” data tables that draw from multiple sources.  Users can create emails and landing pages and preview how they would appear on different devices, although the system-generated contents don't automatically reformat the outputs to fit the viewing platform (a.k.a., "responsive design").  The system can deliver emails and support real time interactions across other channels. Messaging and real-time interaction are software-as-a-service only, while other components can run on-premise or be hosted by the vendor. The system can run on SQL Server as well as Teradata’s own database, and can interact with data stored in Oracle, SQL Server, and Teradata.

The Marketing Operations and Digital Messaging components of Teradata’s Marketing Cloud are similarly advanced. The company this week announced enhancements to both, including new interfaces, collaboration tools, a central repository for marketing assets, and tighter integration with Campaign Manager. The underlying theme is providing a more comprehensive, shared view of customer behaviors across all channels and connecting marketing costs with results to enable more accurate return on investment calculations.

All of this doesn't come cheap: Teradata aims at clients with at least $500 million revenue and sets is prices accordingly.  But large, sophisticated marketing organizations that need a large, sophisticated marketing system should keep Teradata on their list of options.


Friday, March 07, 2014

Ontraport Revamps Its Small Business Marketing Automation System

It’s five long years since I wrote a detailed review of OfficeAutoPilot (now Ontraport), which is a lifetime in industry terms. But, while the product has steadily expanded its features during that period, the basic interface and structure have remained unchanged. I speak with particular authority here, since Ontraport is the marketing automation system of record at Raab Associates – in part because they give me a free account, but mostly because it has the particular mix of email, Web forms, order processing, automation, and WordPress integration that suits my needs and have provided great customer support. Nor does it hurt that I enjoy their corporate sense of humor – see their recent announcement of integration with Wistia for video display, featuring 9-year-old “Girl CEO” Phoebe Ray, daughter of the company founder.

Great customer support has been important because setting up work flows in Ontraport, such as order processing for the VEST report, was pretty darn complicated. It was especially hard for someone like me who only touches those features once or twice a year. Ontraport recognized the issue some time ago and has in fact been working on a complete rebuild for more than two years. They finally released it last week, at least for new clients. Existing installations will be converted over the next few months. But I saw a beta version some time ago and it looks like a major improvement.


The basic workflow approach is still the same: customers define a list of steps without a graphical flow chart. This is somewhat simplistic but adequate for most small businesses. What’s changed is that emails within the workflow are now read from a central library, avoiding the common mistake (at least by me) of editing the library copy without realizing that the system sends a separate copy stored within the workflow itself. The other big improvement, also a pain point for Yours Truly, is that data capture forms and order forms are now the combined: previously, they were created and stored separately. The new version also allows users to store incomplete steps while building a sequence, to assign actions to different task outcomes, and to track response using Google Analytics tags. Those haven’t been issues for me personally but they should be valuable to others. Ontraport can now send and receive SMS messages as well.

I’m only talking here about new enhancements. Ontraport already provided rich features for CRM, task management, marketing automation, order capture, and partner and membership programs. An open API lets it integrate with third-party systems for shopping carts, payment processing, and webinars, as well as with WordPress for Web content management and Facebook for social sign-on. In addition to email and SMS, the system supports postcard mailings through integration with a network of printers. Beyond standard customer support, users can pay a “concierge service” to execute projects for them. Pricing remains a very affordable $297 per month for up to 25,000 contacts, 100,000 emails per month, and two users.

Ontraport reports about 5,000 clients, about half of whom are on SendPepper, a lower priced system for email, postcards, and landing pages. This makes it one of the industry's larger vendors, although the company has kept a relatively low profile.  It’s certainly worth a look if you’re in the market for a small business all-in-one sales and marketing system.

Tuesday, March 04, 2014

Vendemore Moves B2B Display Ad Targeting Towards the Bottom of the Funnel

My post last month on DemandBase and Bizo’s products to target Web display ads at individual businesses resulted in a call from Vendemore, a Stockholm, Sweden-based firm that has been providing similar services for seven and a half years. Like the other firms, Vendemore uses IP address to identify the company of Web site visitors, spots visitors of interest to its clients, and sends targeted ads to those visitors. This can happen via real time bidding for ads on external Web sites or on the client’s own home page. Vendemore can also use cookies to identify site visitors for retargeting on other Web sites within an ad network.


Users can assign spending limits, frequency caps, and ad contents to individual businesses or to lists of businesses. API integration with CRM and marketing automation systems also lets those systems assign businesses to the target lists. This allows marketers to send different contents to companies as the marketing automation system tracks them through different stages of the buying process. Vendemore has also developed standard formats for channels including YouTube, Twitter, Facebook, blogs, and surveys, making it easy to convert existing content into advertisements. It provides more global coverage than U.S.-centric DemandBase and Bizo.

It's tempting to position Vendemore and similar firms at the top of the marketing funnel, as a way to connect with new prospects that have not yet identified themselves to a company. This would offer a simple narrative about expanding B2B marketing automation beyond its home base in the middle of the funnel, where it nurtures known leads. But that’s not quite right. Vendemore CEO Christopher Engman says the system is used primarily to reach people at firms which have already begun a buying process. He said the other most common applications are to encourage cross selling within existing client accounts and to reach potential users at firms that have authorized corporate purchases of a product but left the actual buying decisions to individual divisions or departments. In each case, the systems reaches people at target firms who can't be identified by the sales force or marketing automation.  In two of those three cases, the result is actually to move further down the funnel, to existing customers, rather than higher up.

Looking even further down the funnel, today also brought an announcement by retention specialist Optimove of its new ability send retention messages via paid online advertising, in the form of Facebook Custom Audiences. I’ve recently had some other conversations as well about using marketing automation to support retention campaigns.

So we are indeed seeing an expansion of marketing automation along two dimensions: beyond email to media such as paid advertising and Web personalization, and down the funnel towards customer growth and retention. The move down-funnel makes particular sense because it leverages the known individuals present in the marketing automation database.

I still do expect to see marketing automation systems move up-funnel towards acquisition.  This will use paid advertising and social media, supported by unified databases built with Customer Data Platforms. But apparently it will happen later than I had expected.  After all, it's easier to add value when selling to existing customers, there are fewer synergies between acquisition and marketing automation (i.e., no known individuals to leverage), and marketing automation is run by different people than paid advertising and social media. If you’re sniffing around for the Next Big Thing, this suggests you might turn your nose in a slightly different direction.

Monday, February 24, 2014

Oracle Buys BlueKai and Puts Marketing Databases In the Spotlight

Oracle announced this morning  that it is buying BlueKai, a leading Data Management Platform (DMP) technology vendor and operator of one of the largest data marketplaces. Since I just wrote last Friday about how DMPs integrate with marketing automation to unify customer treatments in Web advertising and direct channels, I’m tempted to just point you to that post for an explanation of how this works and why it matters. I’m also tempted to remind you that I predicted this convergence as an industry trend back in December.  But instead I’ll expand a bit on the fundamental significance of this deal – which is that it promises a serious step toward solving the fundamental problem that increasingly hobbles advanced marketing technology: lack of a solid underlying customer database.


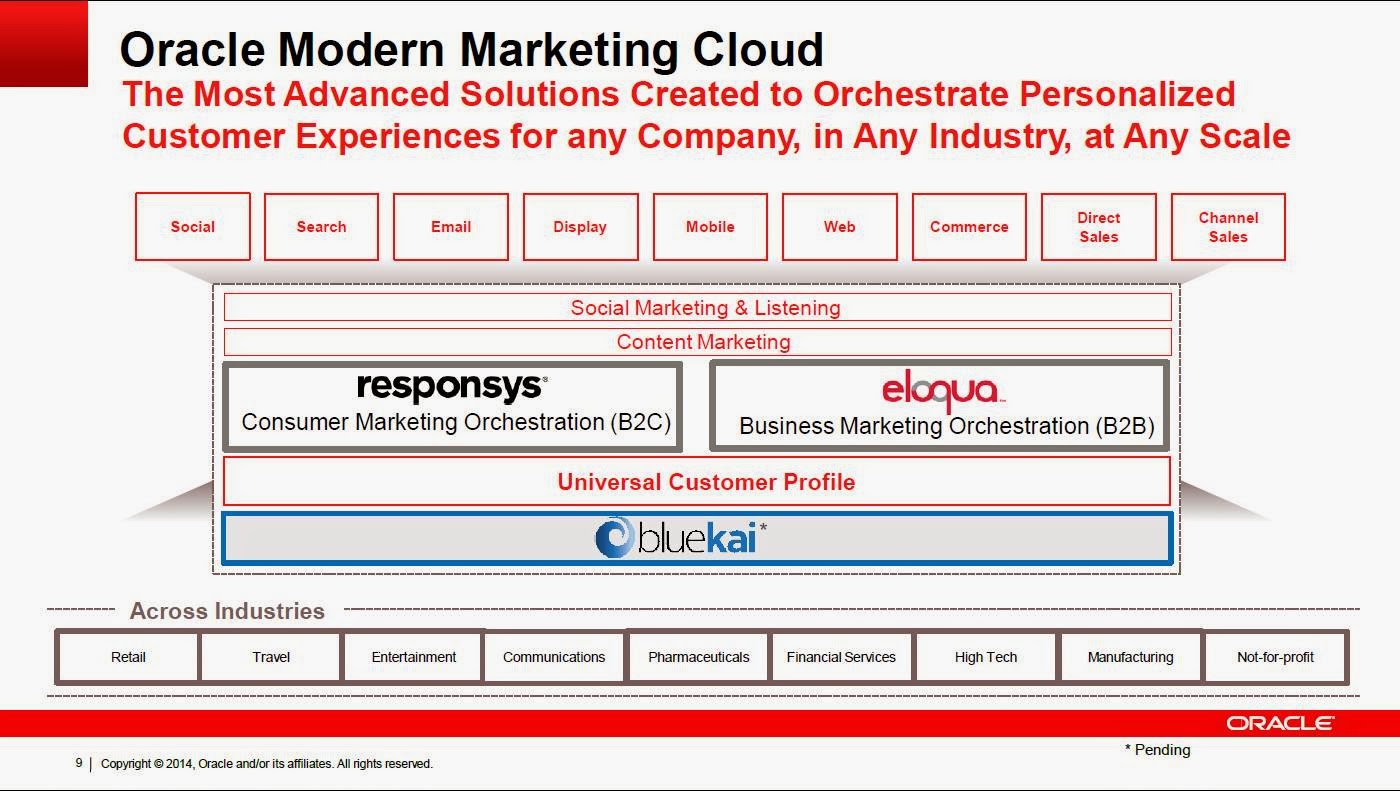
If you look at Oracle’s diagram of their newly expanded Marketing Cloud, you’ll see BlueKai sitting beneath Responsys and Eloqua, providing a “universal customer profile” that allows them to act as “marketing orchestration” systems which, in turn, support programs across all channels – social, search, email, display, mobile, web, commerce, direct sales, and channel sales.

“Marketing orchestration” is a considerable jump beyond the traditional role of “marketing automation”, but I’ll save that analysis for another day. What matters right now is that Oracle places BlueKai exactly where I’ve been placing the Customer Data Platform: as a multi-source database that feeds unified customer data to marketing applications.

This is the first time we’ve seen a major enterprise software vendor draw that picture quite so clearly. More typically, they just do some hand waving around the customer database without explaining how it magically appears. Deep in their hearts, what they really hope is that the database for their core application – CRM, email, Web site management, whatever – will be that central, shared database.  They hope this even though their application doesn’t really provide the database management tools needed to make it happen, and their database itself is often tailored too narrowly to the specific application to support the full range of other uses.

BlueKai, on the other hand, is all about the data. Like other DMPs, it is still mostly organized around cookies and advertising audiences, but it does offer the ability to import other types of data and can certainly track identified individuals if the user wants. The fact that it can combine anonymous and identified profiles is extremely important if marketers are to build a single unified customer data repository and use it to support all contact channels, including Web advertising. The fact that it’s a distinct, named product gives that central customer database the prominence that it deserves.

In short – and I don’t use this term loosely – the BlueKai acquisition could truly be a “game changer” that forces other enterprise software vendors to also give marketers the CDP-style database building tools they’ve needed so desperately. As of this morning, Oracle’s competitors have a new gap in their product lines. It will be interesting to see how they fill it.


Friday, February 21, 2014

Bizo and DemandBase Lead B2B Marketing Automation to Web Advertising and Beyond

I had a fascinating chat earlier this week with a client who described his vision for using DemandBase to tailor messages to Web site visitors from target accounts, using Bizo to further tailor messages to individuals by title, using all this data to synch inbound and outbound campaigns in Eloqua, and eventually driving everything with predictive model scores from a tool like Lattice Engines. That could serve as a pretty complete summary of the state of the art for B2B marketing today, especially if you consider “content marketing” as implicitly included. Equally helpful to me personally, it reinforced my intention to write about Bizo and DemandBase, both of which have recently briefed me on their latest product extensions.

Let’s start with DemandBase. Astonishingly, four years have passed since I last wrote about them. In that time, they’ve continued to build applications that exploit their core technology for identifying Web site visitors by company based on their IP address. This started by providing visitor lists and real-time alerts to sales people who were interested in specific accounts. It later extended to returning visitor attributes in real time so companies could pre-fill forms and personalize Web pages to match visitor interests.  The most recent expansion went beyond a company’s own Web site to the much larger world of online advertising.

To reach that market, the company had to build its own version of “data management platform” (DMP) systems that manage lists of known entities, recognizes them when they appear on an external Web site, and delivers them an appropriate advertisement. The big difference is that DemandBase entities are companies identified by IP address, while traditional DMP entities are cookies attached to browsers (and assumed to relate to individual human beings). DemandBase had to build its own engines for real time bidding (RTB) and ad serving (Demand Side Platform or DSP) to support its approach. These can integrate with Demandbase’s own network of Web publishers that will accept its ads and with other ad exchanges that connect to their own, larger publisher networks.

Data in the DemandBase DMP comes from both DemandBase and clients. The DemandBase data are the company-level attributes that DemandBase has long assembled: company name, industry, revenue, employees, technologies used, etc. Some of this, such as DUNS Number, is purchased from external sources and requires extra payment. The client data, which of course is available only to the client who provided it, could be anything but is usually attributes such as account type, buying stage, and sales territory. The system doesn’t store any information about individuals. Marketing automation, Web analytics, and Web content management systems can all access this data via API calls for analytics and as inputs to their own selection and treatment rules. Outside the DMP itself, DemandBase can store content and decision rules to guide bidding and select which ad is displayed to each account.

So much for the mechanics. The business value is that DemandBase is allowing marketers to tailor messages to target accounts even before they engage directly with the company, thereby (hopefully) luring new prospects into the top of the funnel and engaging them if they don’t respond. This is a major extension beyond traditional marketing automation, which works mostly through email to known prospects.  It also goes beyond Web site personalization, which requires people to at least visit your Web site and in most cases actively provide information about themselves. As you might imagine, DemandBase offers many case studies to show how much this improves performance.

Bizo comes at Web advertising from the traditional route of building a pool of cookies and assembling them into audiences based on the attributes of the individuals they represent.  The pool was originally used to target display advertising and retarget site visitors by sending them ads on other sites. The company says it has pulled data from 4,200 publishers and other sources to identify about 120 million individuals worldwide, including 85 million within the U.S. The number of actual cookies is higher still.* Profiles contain titles and business demographics such as industry, but no personally identifiable information such as names or addresses.

Like DemandBase, Bizo has found many applications for its core data asset. These now extend beyond display ads to social media advertising through Facebook and LinkedIn, Web site personalization through Adobe, Web analytics through Google Analytics and Adobe, and integration with Salesforce.com CRM, BlueKai DMP, and Eloqua marketing automation. Other partners will be added over time.

I’ll assume the Eloqua integration is most interesting to readers of this blog. Basically, it lets Bizo read audience segments created by Eloqua.  Bizo then matches segment members to Bizo identities and delivers Web site, advertising or social messages tailored to each segment. Because Eloqua captures such detailed information about prospect behaviors, this allows highly tailored advertising that is tightly synchronized with prospects’ progress through buying stages and marketing automation campaigns. Since it’s driven by cookies, it can send messages to anonymous as well as identified prospects – a huge expansion in marketing automation’s reach. Bizo can even allocate advertising spend across the different media to achieve reach and frequency targets as efficiently as possible. To encourage this approach, its pricing is based on the number of unique individuals that marketers manage in its system, rather than impressions or ad budget.

The business value offered by Bizo is similar to DemandBase: reaching prospects that haven’t yet engaged with a company directly or retargeting them when they don’t respond. The different technical approaches have their own strengths and weaknesses: IP-based identification is relatively stable but works only at the company level and doesn’t identify small businesses that lack their own stable IP address; cookies identify individuals but are often deleted, miss some people, and result in multiple, fragmented identities for others. Like the client I mentioned at the start of this article, you can probably think of them as complementary rather than competing components of a complete B2B marketing solution.

________________________________________________________________________
* Given that the total employed U.S. workforce is about 145 million, I suspect that 85 million contains quite a few duplicates, meaning any one profile captures just a fragment of an individual’s activity. But that’s the nature of this sort of thing; the business question is how well the data works even in its imperfect state.

Thursday, February 13, 2014

Marketing Automation 2014 Industry Overview: What the Surveys Tell Us

The Interwebs have delivered an unusually rich trove of data about the marketing automation industry in the past few weeks. Other than Raab Associates’ own VEST report, we’ve seen surveys of active buyers from Software Advice, usage figures based on direct observation from Mintigo  and Venture Beat (using Datanyze), and another broad-based survey from Pepper Global and Holger Shulze. Taken together, these provide a clearer picture than usual of the state of marketing automation. Here’s how I see things.

Strong Growth Continues

As I reported last week, I expect industry revenue to grow 60% in 2014, accelerating from the already-impressive 50% per year we saw in 2012 and 2013.


The main basis for my prediction is high growth that vendors reported in 2013, and in particular a trend towards higher revenue per client among the vendors who share that information with me.


These include:
  • HubSpot (50% revenue growth on 25% client growth)
  • Act-On (115% revenue growth on 59% client growth)
  • SalesFUSION (100% revenue growth on 47% client growth)
  • Marketo (64% revenue growth on 30% client growth)
Lots of Opportunity Remains

My VEST data suggests that maybe 3% of micro-businesses (under $5 million revenue) now use a marketing automation system, and under 10% of larger firms do.


This varies hugely from the usual survey results, which often show something like 50% penetration.  The reason is selection bias: most surveys are answered by people who are actively engaged in marketing automation.  They are vastly more likely than average to have a system in place.


The Mintigo results confirm this.  Mintigo’s technology scans the Internet for things like job listings and Javascript tags and infers from those which products are used at every company it finds. There’s still a bit of selection bias – it won’t work if a company isn’t on the Internet – but the impact is obviously much less. Mintigo’s conclusion across 186,500 B2B companies was that just three percent were using the most common marketing automation systems: Oracle Eloqua, Marketo, HubSpot, and Salesforce.com Pardot. Penetration reached eight percent among larger firms and varied substantially by industry.


Mintigo sagely warns that industry penetration rates are not the same as share of marketing automation customers, since some industries are bigger than others. Software Advice does show the number of prospective buyers by industry: not surprisingly, tech is still the most common industry among new buyers.  But more interesting is that 77% come from somewhere else. I don’t have any historical data available but strongly suspect it would confirm that the industry is increasingly selling outside its original base of tech clients.


Users Want Core Marketing Automation Features

Both Software Advice and Pepper Global asked what features marketing automation buyers want. This is a pretty common question so the answers were not very surprising.  In fact, what was most impressive was the relative consistency of the rankings, with ead nurturing, analytics, and lead scoring at the top in both surveys, email and campaign management in the middle, and list segmentation is at the bottom.

Those top three are the key improvements that marketing automation provides over simple email or CRM systems, so this prioritization makes sense. It was intriguing to see inbound marketing and social media marketing ranked so low on the Software Advice data – I read this to mean that marketers already get them from systems outside of marketing automation and don't see much need for a change.  Similarly, the Pepper Global data’s low ratings for lead activity tracking, lead capture, and Website visitor tracking reflect that marketers have systems in place for those.


Features Don't Drive Decisions ...or Create Success

Pepper Global also asked some interesting questions about evaluation criteria and obstacles. Again, there were no particular surprises in the answers – marketers care more about cost, integration, and ease of use than vendor or technical details. (I guess meeting functional requirements is assumed.) Similarly, it’s no surprise to see the biggest obstacles are budget, employee skills, data quality and content.  The two sets of answers do correlate (budget relates to cost; employee skills relates to ease of use), which is reassuring.


But take a closer look.  Did you notice how few of these obstacles can actually be addressed by marketing automation functions?  The real issues are budgetary (budgets and content), organizational (skills, data quality, sales feedback, sales integration, and performance standards), and technical (data collection and compatibility). This has practical implications for how marketing automation vendors should position themselves, invest in product development, and supplement their products with services.


Pepper Global also makes some intriguing observations about differences in responses from small businesses vs. mid to large businesses: cost and budget are the biggest issues for small business, while integration and analytics matter more to bigger companies. Sadly, they didn't publish additional details. Still, it’s worth being reminded that these differences exist and should be considered by vendors in their planning and by marketers in their system selection.

The Real Competition Isn't Other Vendors

As the industry penetration figures indicate, the real competition in most marketing automation purchases is a different technology, not another marketing automation vendor. Software Advice drives this point home by showing how prospective buyers are currently managing marketing activities: nearly half are relying on a CRM. A surprisingly small fraction cite email, although presumably they all have email capabilities.  I'd guess this is because they are answering specifically about marketing management.  If I were an email vendor, I'd think about that one.


Given the industry's low over-all penetration rate, it's interesting that nine percent of prospective buyers are looking to replace an existing system.  This suggests they like the idea of marketing automation but aren't happy with their particular product.  Sure enough, just over ten percent of the buyers say they're evaluating a new system for exactly that reason.  But the much more common reasons apply to people with no marketing automation in place: improve lead management, automate processes, and get more/better features than current [non-marketing automation] tools.


Market Share Varies by Sector

Narrowing the focus to existing users, Venture Beat and Pepper Global both have some data, as does the VEST. Remember that these come from different sources:

Venture Beat uses Datanyze to read the actual systems that are embedded in marketers’ web sites.


Pepper Global is based on a survey of the B2B Technology Marketing Community on LinkedIn.


VEST data is self-reported by the vendors.


Mintigo’s technique would also reveal market share but they have diplomatically chosen not to share.


The results are broadly consistent once you take into account that Pepper Global’s sample has many fewer small companies than Venture Beat, and thus understates clients for vendors like HubSpot and Infusionsoft. One extremely important caveat is that these figures are counting clients, not revenue: HubSpot has three times as many clients than Marketo but 10% less 2013 revenue. (The revenue figures aren't on the chart but are public: $77.6 million for HubSpot and $85.1 million for Marketo.)  As the Pepper Global slide suggests, different vendors are strongest in different customer segments.


Lots of Choices

There are plenty of vendors beyond the handful of industry leaders. The Venture Beat slide lists some; we report on a good number of them in the VEST; and I've written about others on this blog. Here’s a list I recently pulled together, along with client self-reported counts. It still leaves many out.


Why would anyone pick a vendor other than the leaders? One answer is, because they don’t know anyone else: some vendors still tell me more than half their deals are uncontested, meaning they are selling against doing nothing or an incumbent CRM or email system. Presumably this will become less common as more marketers realize that marketing automation systems are a category with lots of options.

Another, better answer is that the systems really are different. Sure, all marketing automation products share the same core features: email, landing pages and forms, web behavior tracking, nurture campaigns, lead scoring, CRM integration, and reporting. But there are still significant differentiators.  In fact, I'd argue these are becoming increasingly important as ways for new and smaller companies to find niches where they can compete. Here’s a list of some of the approaches and a sample of vendors who have taken them. (Many vendors would fit into multiple categories; pardon the oversimplification.)
 

Note that just about everyone cites low cost and ease of use, as they should: they're what buyers say are most important.  But this means those claims pretty much cancel each other out, regardless of the underlying system's actual merits. This leaves more concrete differences, some based on features and others based on service or distribution models. Even the surveys showed that features alone will rarely drive a decision, the exceptions are features that are absolute requirements and hard to find, such as integration with a particular CRM system or support for channel partners.  So far, every differentiator on this list can point to at least some measure of success.

So there you have it, folks: my current snapshot of our rapidly changing industry.  Thanks to Mintigo, Software Advice, Venture Beat, Pepper Global, and all the other people who publish such great data.


Thursday, February 06, 2014

Genius and LoopFuse Are Acquired; Leadsius Picks Up the Freemium Banner

The past week has seen two acquisition announcements in the B2B marketing automation space: LoopFuse by SalesFUSION  and LeadRocket/Genius by CallidusCloud, which owns LeadFormix. Both of the acquired vendors had bright prospects at one time but fell by the wayside. Interestingly, both pursued a “freemium” strategy of offering their system for free to users with small databases. The goal is to build a big base of users, some of whom will eventually pay real money for a larger installation. Since both vendors ultimately failed to survive, it might seem reasonable to conclude that freemium doesn’t work for B2B marketing automation, despite its successes elsewhere.

But this week also saw the start of a big freemium push by Leadsius, a new small business marketing automation vendor I wrote about two weeks ago. Leadsius reports more than 1,200 freemium accounts since they started offering them a bit over a year ago. Can they succeed where Genius and LoopFuse did not?

Obviously I don’t know, but it’s fair to say that the odds are against them. Genius and LoopFuse were both good products run by smart people backed by venture funding (a lot for Genius, a little for LoopFuse). Each reported thousands of freemium sign-ups that converted to paid accounts at a reasonable rate – “reasonable” being defined as an acceptable cost per new customer when the cost of the freemium accounts was included. The problem seemed to be that the absolute number of converted accounts wasn’t high enough to sustain the business, and neither vendor had enough business coming in from other sources. I’d also guess that freemium appealed most to small companies which didn’t generate much revenue even after they started to pay.  (Even though many freemium users are departments within large companies, I'd suspect those firms buy different, enterprise-level systems when they decide to make a real commitment.)

Freemium is a much-discussed topic in tech circles, and there are many people who have thought more deeply about it than I have. My casual impression is it probably makes the most sense when there’s a network effect, meaning you need to attract lots of users quickly to succeed. Obviously it needs to be a product that’s easy to learn and use, so training and support costs are kept at a minimum.

My take is that freemium doesn’t fit well with marketing automation because marketing automation takes a lot of work to use effectively. Compare this with email and Web site hosting, where freemium has worked well: casual users can be quite successful with those products. In fact, the trend in the marketing automation industry has generally been to increase rather than remove barriers to getting started, by doing away with options such as 30 day free trials or free implementation support. Vendors like HubSpot and Infusionsoft have tried many approaches but ended up requiring significant up-front investment from new clients, specifically to screen out buyers who won’t put in enough work to succeed. That’s about as far from the freemium approach as you can get.

None of this means that Leadsius is set to fail. They might find a way to make freemium work or they might abandon freemium and succeed doing things the old fashioned way. From a prospective buyer’s perspective, what really matters are the quality of the system and the pricing, which are quite competitive. So long as they’re willing to learn from experience – and abandon freemium if that is what experience teaches – their prospects are bright.

Tuesday, February 04, 2014

New Raab VEST Report: B2B Marketing Automation Will Reach $1.2 Billion in 2014


I’ve just published the latest edition of our B2B Marketing Automation Vendor Selection Tool (VEST), with updated entries on all your favorites and several new entries to boot. This is always a fun project because it gives me an overview of what all the vendors have been up to for the past six months. A few interesting trends stood out:

  • revenue growth is accelerating. My data are a little less comprehensive than previously because several of the big vendors are now part of public companies and don’t share detailed information. Those that did provide information showed great growth in 2013, in most cases over the 50% I had predicted for the industry as a whole. Even more interesting, nearly everyone reported faster growth in revenue than in clients: to take one vendor that does provide statistics, HubSpot recently reported  50% revenue growth vs. 25% growth in number of clients. In their case and others, the reason seems to be a combination of larger size deals on new customers and growth in billing to existing customers. Based on this data, I’m projecting a 60% increase in industry revenue for 2014, to $1.2 billion. You heard it here first.
  • the hot new feature is…SEO content rating. Yes, there’s continued growth in various aspects of social media marketing and in mobile-friendly content creation.  That’s old news. What I hadn’t realized before is that at least a half dozen vendors had added or improved features to help marketers build content that attracts search engine hits on selected keywords or concepts. I suppose that’s become increasingly important as marketing automation moves beyond its original role in lead management to help attract new leads at the top of the funnel. (Do I get SEO credit for using “top of the funnel”?)
  • lots of new vendors. I added four new vendors to the report, all of which have just begun to market their products aggressively. None is very large yet, except for SimplyCast, which won’t release precise data but did say it has 3,000 to 5,000 customers for its multi-channel customer management system (you may recall that I reviewed them briefly last week.) The new systems offer a broad range of configurations, from ultra-simple interfaces with limited functions to elaborate multi-channel workflows that are correspondingly complex.
  • agency systems are big. Two of the four new vendors are agency system specialists, and several other vendors have also launched special agency editions. This creates some weird feature combinations, since agencies to serve small businesses need administrative features, such as precise user rights management, that are otherwise only used by big enterprises, . Of course, the reliance on agencies is more evidence that many marketing departments still lack the skills needed to do advanced marketing automation on their own – but you knew that.
  • mid-market leadership may be up for grabs. Small but established mid-market firms including SalesFusion and eTrigue have been growing particularly quickly, as has Act-On. This may be because the current mid-market leaders, Marketo and Pardot in particular, have been focusing more on enterprise sales. I had thought that heavy funding would be necessary become a new market leader, which is the way Marketo, Act-On and HubSpot did it. SalesFusion did just take an $8.25 million investment but their revenue doubled last year without it. So perhaps having a good product and being focused will enough for someone new to elbow into a top-three position.  We'll see.
I could go on, but why should David Raab have all the fun? You, too, can uncover exciting industry trends and share them with the world. Just click here to purchase your very own copy of the VEST and analyze to your heart’s content.